Effective cash flow management techniques help a business maintain enough money to pay employees, suppliers, taxes, lenders, and operating expenses at the right time. Profitability matters, but a profitable company can still experience serious pressure when customer payments arrive after major bills are due.
Strong cash flow management focuses on timing, visibility, and control. It helps owners understand where money comes from, where it goes, and when shortages may occur. With a reliable process, businesses can make informed decisions instead of reacting to emergencies.
This guide explains practical cash flow management techniques for startups, small businesses, and growing companies. It covers forecasting, receivables, expenses, inventory, reserves, financing, and the financial metrics that support healthier liquidity.
Why Cash Flow Management Techniques Matter
Cash flow represents the movement of money into and out of a business. Positive cash flow means more money entered than left during a period. Negative cash flow means outflows exceeded inflows.
A short period of negative cash flow is not always a crisis. A company may invest in inventory, equipment, staff, or expansion before receiving the related revenue. The problem begins when the business lacks enough liquidity to meet near-term obligations.
Reliable cash flow management techniques help businesses:
- Pay bills and payroll on time
- Prepare for seasonal revenue changes
- Reduce dependence on emergency borrowing
- Negotiate with suppliers from a stronger position
- Invest in growth with greater confidence
- Identify financial problems before they become urgent
- Build resilience during unexpected disruptions
Cash Flow Is Different from Profit
Profit is calculated by subtracting expenses from revenue under accounting rules. Cash flow tracks the actual timing of money received and paid.
For example, a business may record a large sale this month but offer the customer 60-day payment terms. The sale improves reported revenue immediately, but the cash may not arrive for two months. Meanwhile, wages, materials, rent, and taxes may already be due.
Build a Rolling Cash Flow Forecast
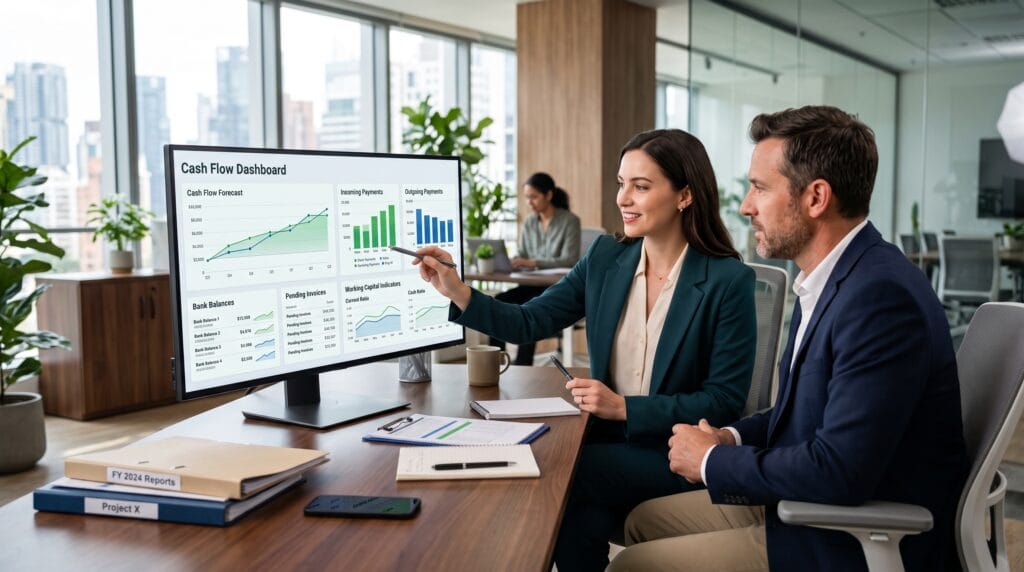
Forecasting is one of the most useful cash flow management techniques because it transforms financial data into an early-warning system. A rolling forecast shows expected cash receipts, expected payments, and the projected closing balance for each period.
Use a 13-Week Forecast
A 13-week cash flow forecast is detailed enough to support weekly decisions while remaining manageable. It is especially useful for businesses with tight liquidity, irregular sales, or rapidly changing expenses.
Include the following categories:
- Opening bank balance
- Customer payments by expected date
- Cash sales and recurring revenue
- Payroll and contractor payments
- Supplier and inventory payments
- Rent, utilities, subscriptions, and insurance
- Loan repayments and interest
- Taxes and statutory obligations
- Capital purchases and owner distributions
- Projected closing cash balance
Update Forecast Assumptions Weekly
A forecast becomes less useful when it is treated as a one-time spreadsheet. Update expected payment dates, new sales, delayed invoices, expense changes, and unexpected commitments every week.
Compare the forecast with actual results. The differences reveal where assumptions are too optimistic, where costs are rising, and which customers regularly pay late.
Create Best, Base, and Worst-Case Scenarios
Scenario planning improves preparation. A base case reflects the most likely outcome. A best case assumes stronger collections or sales. A worst case includes delayed payments, weaker revenue, or higher costs.
The purpose is not to predict the future perfectly. It is to identify the decisions required under different conditions.
Also Read: 10 Smart Ways To Budget For Small Business Growth
Accelerate Accounts Receivable
Sales do not support operations until the business receives the money. Improving accounts receivable is therefore one of the fastest cash flow management techniques available to many companies.
Invoice Immediately
Send invoices as soon as work is completed, products are delivered, or milestones are approved. Waiting several days to invoice automatically delays payment.
Invoices should clearly show:
- Customer name and billing details
- Invoice number and issue date
- Description of products or services
- Amount due and applicable taxes
- Payment deadline
- Accepted payment methods
- Bank or payment instructions
- Contact information for billing questions
Set Clear Payment Terms
Use payment terms that match the company’s operating cycle. A small service business may prefer payment on receipt, deposits, milestone billing, or 14-day terms instead of automatically offering 30 or 60 days.
Communicate terms before work begins. Customers are more likely to follow expectations that were agreed upon in advance.
Use Deposits and Progress Billing
Deposits reduce the amount a business must finance before completing a project. Progress billing aligns payments with major stages of work.
For long projects, a practical structure may include:
- An upfront deposit before work starts
- A second payment after the first major milestone
- A third payment after delivery or implementation
- A final balance after approval
Create a Consistent Collection Process
Late-payment follow-up should be systematic rather than emotional. Send a reminder before the due date, another on the due date, and scheduled follow-ups after the invoice becomes overdue.
Escalation may include a phone call, suspension of additional work, a revised payment plan, or formal collection procedures. Document every communication.
Control Cash Outflows Without Damaging Operations
Reducing costs can improve liquidity, but indiscriminate cuts may weaken service, sales, or productivity. Better cash flow management techniques distinguish essential spending from low-value spending.
Classify Expenses by Priority
Group expenses into four categories:
| Expense Category | Description | Recommended Action |
|---|---|---|
| Essential | Payroll, core suppliers, rent, taxes, insurance | Protect and forecast carefully |
| Revenue Supporting | Marketing, sales tools, delivery capacity | Measure return and optimize |
| Useful but Flexible | Training, travel, optional software | Delay or reduce when necessary |
| Low Value | Unused subscriptions, waste, duplicate services | Cancel or eliminate |
Review Recurring Expenses
Small recurring charges can accumulate into a significant monthly burden. Review software, memberships, storage, telecommunications, professional services, and automatic renewals at least quarterly.
Look for unused licenses, duplicate tools, old contracts, and pricing plans that no longer fit the business.
Negotiate Supplier Terms
Supplier negotiations can improve cash timing without reducing necessary purchases. Ask for longer payment terms, staged payments, volume discounts, or pricing based on predictable order schedules.
Do not delay payments without communication. Reliable relationships create more flexibility when the company genuinely needs support.
Improve Inventory Cash Flow
Inventory converts cash into products that may remain unsold for weeks or months. Businesses that carry stock need disciplined purchasing and inventory management.
Identify Slow-Moving Inventory
Review inventory by sales velocity, margin, age, and seasonal relevance. Slow-moving items may require discounts, bundles, alternative sales channels, or reduced future ordering.
Set Reorder Points
A reorder point balances availability with cash efficiency. It considers average demand, supplier lead time, and an appropriate safety stock level.
Ordering too early locks cash in stock. Ordering too late can cause missed sales and expensive emergency purchases.
Use Smaller, More Frequent Orders
When suppliers allow it, smaller orders may reduce the cash tied up in inventory. The business must compare this benefit with shipping costs, minimum order requirements, and potential quantity discounts.
Maintain a Cash Reserve
A reserve gives the company time to respond when revenue declines or expenses increase unexpectedly. It is one of the most protective cash flow management techniques because it reduces the need for urgent, expensive financing.
Set a Practical Reserve Target
The right target depends on the stability of revenue, fixed costs, customer concentration, seasonality, and access to credit. A business with predictable subscriptions may require a smaller buffer than a project-based company with irregular payments.
Start with a realistic milestone, such as one month of essential operating expenses, and build toward a stronger reserve over time.
Separate Reserve Funds
Keep reserve cash in a separate account so it is not accidentally used for normal discretionary spending. Define the conditions under which the reserve can be accessed and how it will be replenished.
Align Growth Plans with Available Cash
Growth often consumes cash before it produces cash. Hiring, inventory, equipment, advertising, and new locations require upfront funding.
Calculate the Cash Cost of Growth
Before approving a growth initiative, estimate:
- Initial setup costs
- Monthly operating costs
- Working capital requirements
- Expected time before revenue begins
- Expected customer payment timing
- Break-even date
- Downside scenario funding needs
This analysis prevents a company from pursuing profitable opportunities that it cannot safely finance.
Stage Large Investments
Break expansion into smaller phases with measurable milestones. A staged approach makes it easier to stop, adjust, or accelerate based on actual results.
Also Read: The Creative Business Plan Template New Founders Will Finish
Use Financing Before a Crisis
Credit is usually easier and less expensive to obtain when the business is financially stable. Establishing access before cash becomes critical creates more options.
Match Financing to the Need
Different funding sources serve different purposes:
| Funding Type | Best Used For | Important Consideration |
|---|---|---|
| Line of Credit | Short-term timing gaps | Interest and renewal conditions |
| Term Loan | Equipment or long-term investments | Fixed repayment obligation |
| Invoice Financing | Cash tied up in receivables | Fees and customer implications |
| Trade Credit | Inventory or supplier purchases | Supplier relationship and terms |
| Equity Funding | High-growth expansion | Ownership dilution and control |
Avoid using short-term financing for ongoing structural losses. Borrowing can solve a timing problem, but it does not repair an unprofitable business model.
Separate Business and Personal Finances
Mixing personal and business transactions reduces visibility and creates accounting problems. Use dedicated business bank accounts, payment cards, and expense records.
Set a planned owner salary or distribution policy instead of withdrawing money unpredictably. This makes forecasting more accurate and helps protect essential operating cash.
Automate Cash Flow Management Techniques
Automation can reduce errors and improve financial visibility. Accounting and forecasting tools can connect bank transactions, invoices, bills, budgets, and cash projections.
Useful Tool Categories
- Accounting software for transaction records and reporting
- Invoicing systems for faster billing and reminders
- Expense management platforms for spending controls
- Cash flow forecasting tools for scenarios and projections
- Payment processors for faster customer payment options
- Dashboard tools for financial metrics and trends
The uploaded business resources identify forecasting platforms, accounting systems, and cash flow tools as useful components of a modern finance workflow.
Choose Tools Based on the Bottleneck
Do not add software without a defined problem. Start with the largest source of delay or uncertainty, such as late invoicing, poor expense visibility, disconnected bank data, or unreliable forecasting.
Also Read: Tools for Business: A Complete Guide by Category
Track the Right Cash Flow Metrics
Metrics turn cash flow management techniques into a repeatable management system. Review a small set of useful indicators regularly.
Operating Cash Flow
Operating cash flow shows the cash generated or consumed by normal business activity. A consistently negative result requires investigation even when reported revenue is growing.
Days Sales Outstanding
Days sales outstanding estimates how long the company takes to collect customer payments. A rising number may indicate weaker collection practices, changing customer behavior, or overly generous terms.
Cash Conversion Cycle
The cash conversion cycle measures the time between paying for inventory or production and collecting cash from customers. A shorter cycle generally reduces working capital pressure.
Burn Rate and Runway
For businesses spending more cash than they generate, burn rate shows the monthly cash reduction. Runway estimates how long available cash may last at the current burn rate.
Create a Weekly Cash Flow Routine
Consistency is more valuable than occasional intensive analysis. A short weekly review can keep financial priorities visible.
- Confirm the current bank balance.
- Update expected customer payment dates.
- Review invoices due and overdue.
- List payments required during the next four weeks.
- Update the 13-week forecast.
- Compare actual cash with the previous forecast.
- Identify the lowest projected balance.
- Assign actions for any expected shortfall.
- Document decisions and follow up the next week.
Common Cash Flow Management Techniques Mistakes
1. Forecasting Revenue Too Optimistically
A signed contract is not the same as collected cash. Forecast receipts based on realistic payment behavior, not only invoice due dates.
2. Ignoring Taxes
Tax obligations can create predictable cash shortages when funds are not reserved. Move tax amounts into a separate account or include them clearly in the forecast.
3. Growing Fixed Costs Too Quickly
Long-term leases, permanent hires, and recurring contracts reduce flexibility. Add fixed costs only when the company can support them under conservative revenue assumptions.
4. Relying on One Major Customer
Customer concentration creates cash flow risk. A late payment or lost contract can affect the entire business. Diversification reduces dependence on one source of cash.
5. Confusing Bank Balance with Available Cash
The current balance may include money needed for payroll, taxes, supplier payments, refunds, or loan repayments. Use the forecast to determine truly available cash.
Cash Flow Management Techniques Checklist
- Maintain a rolling 13-week cash flow forecast
- Update forecasts with actual results every week
- Invoice customers immediately
- Use deposits and milestone payments when appropriate
- Follow a consistent overdue invoice process
- Review recurring expenses quarterly
- Negotiate payment terms with suppliers
- Monitor slow-moving inventory
- Build and separate a cash reserve
- Evaluate the cash cost of growth
- Establish financing options before they are urgently needed
- Separate personal and business finances
- Track operating cash flow, collection time, and runway
- Hold a weekly cash flow review
Frequently Asked Questions
1. What are the most effective cash flow management techniques?
The most effective techniques include rolling forecasts, faster invoicing, clear payment terms, systematic collections, expense control, inventory discipline, cash reserves, and regular financial reviews.
2. How often should a cash flow forecast be updated?
Businesses with active operations should update short-term forecasts weekly. Stable companies may also maintain monthly and annual forecasts for strategic planning.
3. How can a business improve cash flow quickly?
Immediate actions include sending delayed invoices, following up overdue accounts, requesting deposits, reducing nonessential spending, negotiating supplier timing, and selling excess inventory.
4. Can a profitable business have negative cash flow?
Yes. Profit and cash use different timing rules. A profitable business may have negative cash flow because customers pay slowly, inventory is purchased in advance, debt is repaid, or growth requires upfront investment.
5. How much cash reserve should a business keep?
The appropriate reserve depends on revenue stability, fixed costs, seasonality, customer concentration, and financing access. Many businesses begin with a target based on one month of essential expenses and increase it over time.
Conclusion on Cash Flow Management Techniques
The best cash flow management techniques create visibility before they create restrictions. Forecasting shows when pressure may occur, faster collections improve incoming cash, expense controls protect liquidity, and reserves provide time to respond.
Cash flow management should become a regular operating discipline rather than an emergency activity. By reviewing cash weekly, testing realistic scenarios, and acting early, a business can protect daily operations while creating a stronger foundation for sustainable growth.
Also Read: “Passive Income Ideas to Grow Your Wealth“